We almost didn’t write this piece…yet.
Not because the new federal student loan limits aren’t important. Obviously, they are. But this is very much an evolving story.
On July 4, 2025, the One Big Beautiful Bill Act (OBBBA) was signed into law, bringing significant changes to federal student aid programs. Some provisions took effect immediately, others took effect this summer on July 1, 2026, and more will be phased in over the coming years.
So, there’s still a lot we don’t know—the rules are new, and implementation is evolving. We’re also starting to see students affected by the changes, while some provisions remain in flux.
While some are waiting to see how things shake out before weighing in, institutions and students don’t have that luxury.
Students are already trying to understand what these changes mean for their ability to pay for school. Financial aid teams are fielding questions. Enrollment leaders are thinking about how the changes could affect prospective students. And institutions are being asked to make decisions without the benefit of historical data showing them what these changes will mean for enrollment.
We may not know exactly where the new loan limits will lead. But institutions can—and should—start thinking about what they mean now.
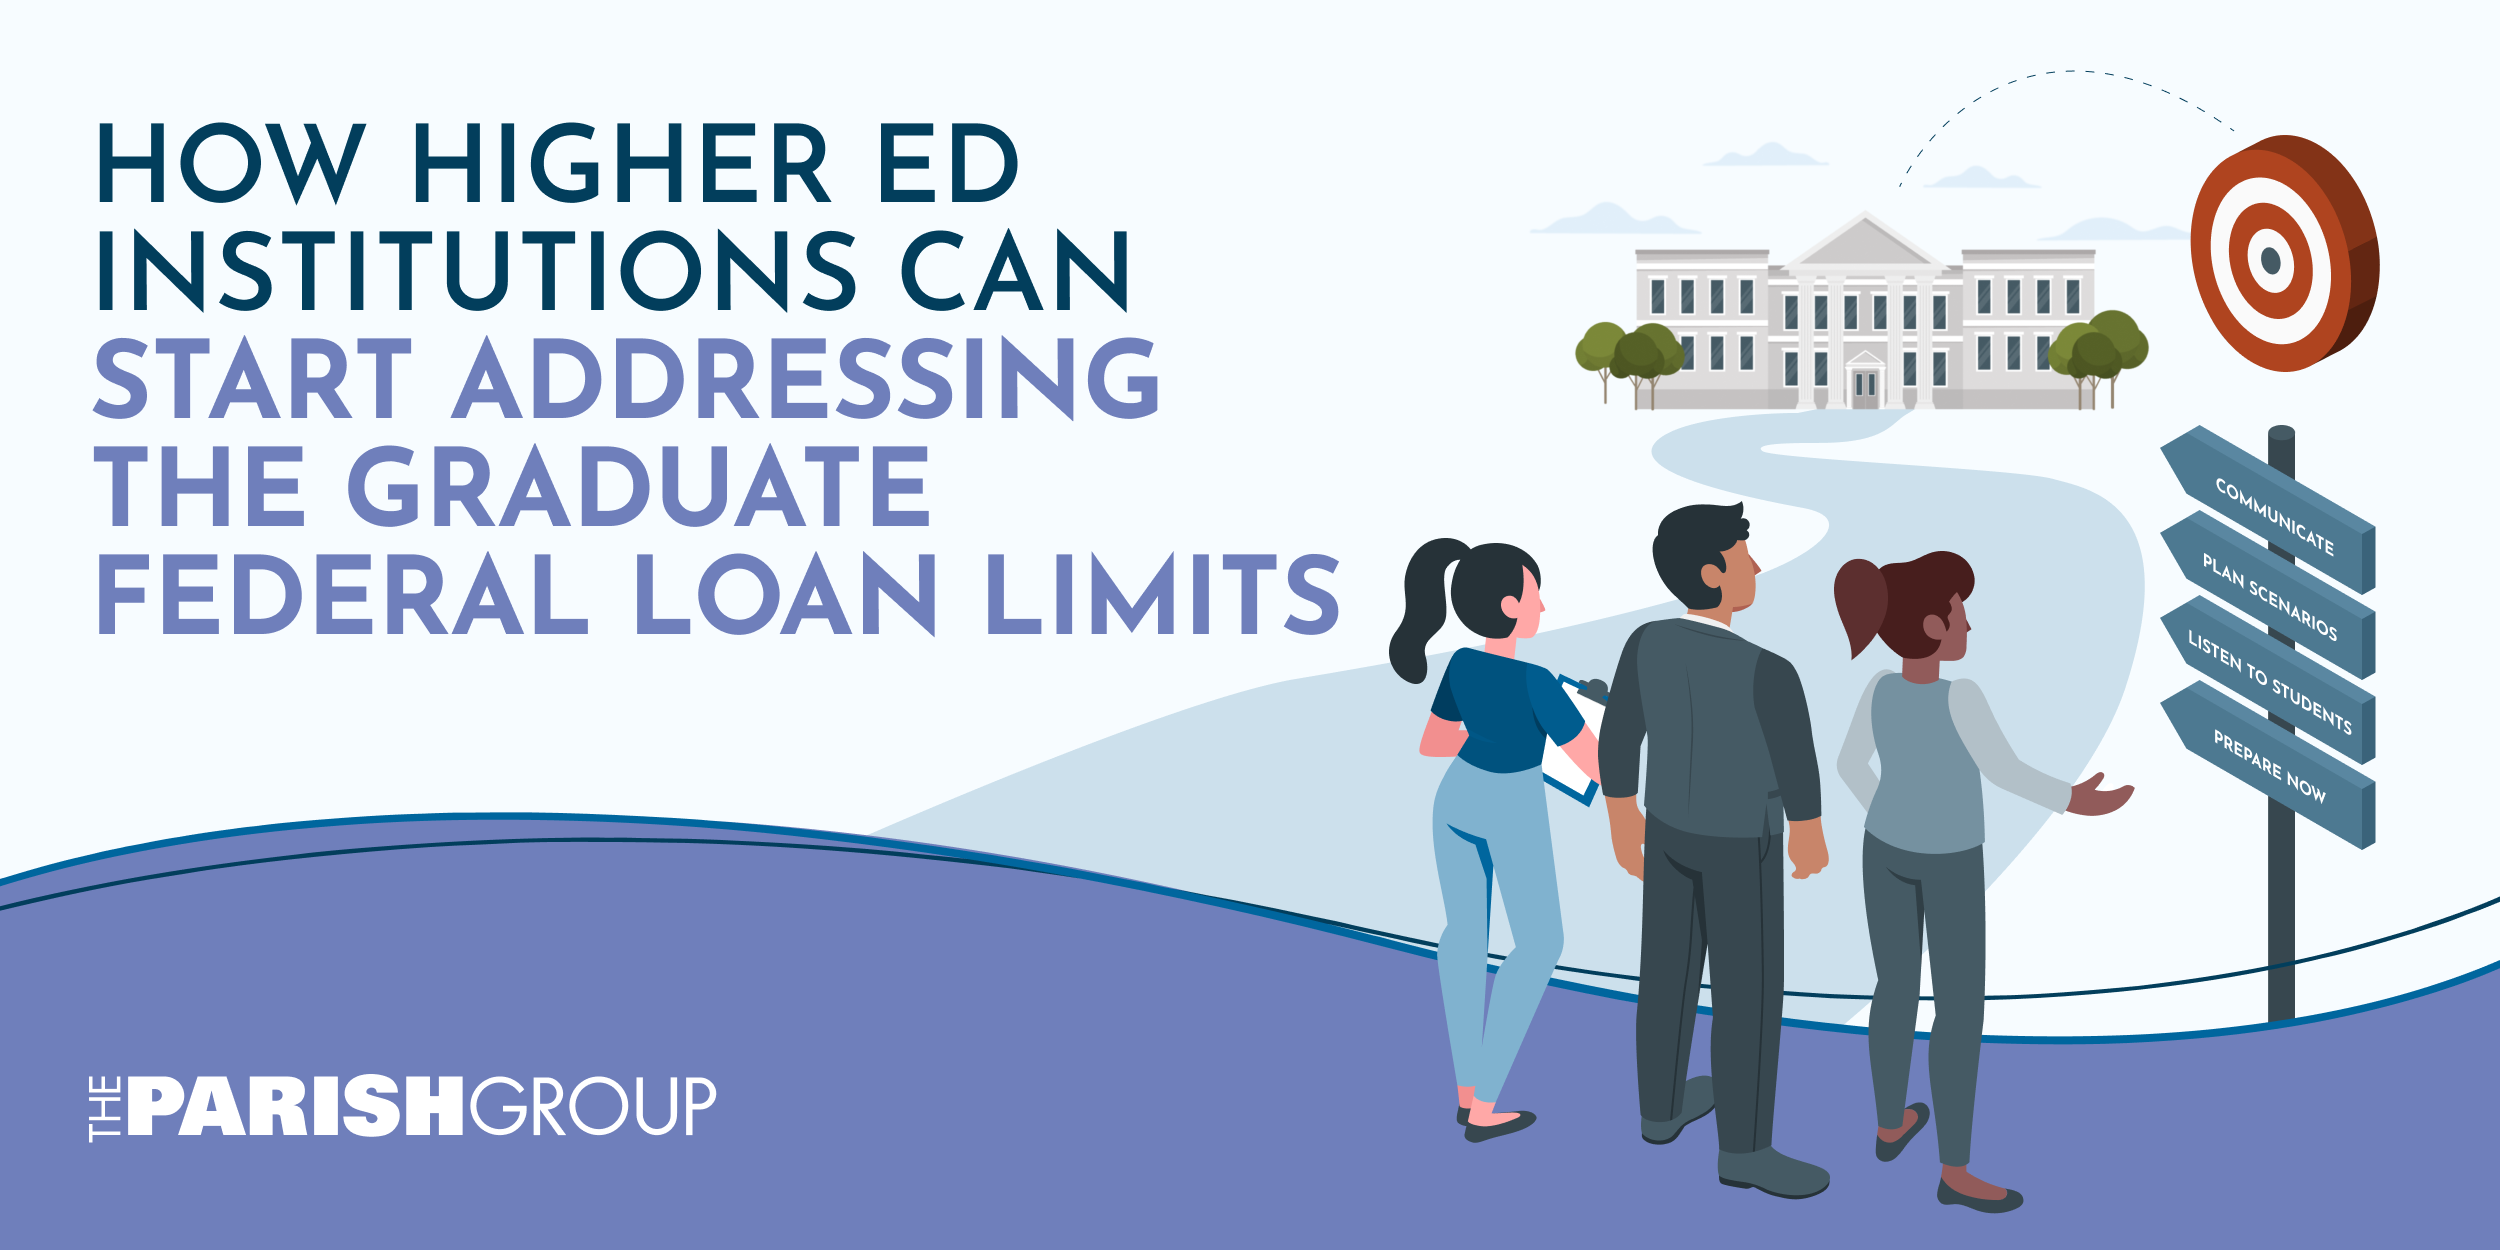
Start by Figuring Out Who On Your Campus Will Be Affected
The impact won’t be the same for every student or program. Beginning July 1, 2026, new federal borrowing limits cap graduate students at $20,500 per year and $100,000 in aggregate, while professional students have higher limits of $50,000 per year and $200,000 in aggregate. The changes also eliminate Grad PLUS loans for new graduate and professional borrowers.
For institutions, the first step is understanding where those limits could create the biggest gaps.
Which programs have costs that exceed the new federal borrowing limits? Which students have historically relied most heavily on federal loans? Where could students face a meaningful difference between what their program costs and what they can borrow?
Institutions may not have definitive answers yet, but they can identify the programs and student populations that appear most exposed. That gives financial aid, enrollment, and academic leaders a starting point for anticipating questions, identifying potential challenges, and deciding where to look more closely.
Communicate Before You Have Every Answer (And Be Transparent About That)
Students don’t need institutions to predict exactly how this will play out. They need help understanding what the changes mean for them, and they need that information as they decide where and whether to enroll.
That means communicating clearly about what is changing, who may be affected, and what students should do next. It also means being upfront when an answer isn’t available yet. With guidance still evolving, institutions can point students to the most up-to-date information and ensure they know whom to contact with questions.
In practice, that could mean creating a central place for updates, designating someone responsible for keeping that information current, and providing financial aid, enrollment, and admissions teams with consistent language to use when questions arise.
Institutions don’t need to have all the answers before they start communicating. They need to be honest about what they know, what they don’t, and where students can go for the latest information.
Start Having the Longer-Term Conversations Now
The immediate question is how institutions can help students navigate a new borrowing environment. The longer-term question is what that environment means for the institution itself.
Schools may not be able to change tuition overnight, but they can start looking at whether their pricing, financial aid, and program structures make sense in a world where students have less access to federal borrowing.
That might mean asking:
- Which programs could become harder for students to finance?
- Where could students face the largest gaps between federal borrowing limits and the cost of attendance?
- Can institutional aid realistically help close those gaps?
- Could program length, delivery, or other aspects of program design affect affordability?
- What could changes in financing mean for enrollment?
These questions can’t be answered by financial aid alone. They require conversations across enrollment, financial aid, academic leadership, finance, and marketing.
Institutions don’t need to make major decisions today. But they can start identifying the scenarios that may require a response—and thinking through what they would do if they occur.
Listen to What Students Are Saying
Institutions will eventually have more data on how the new limits affect enrollment and financing. But they don’t have to wait for that data to start learning from students.
Ask prospective and current students what questions or concerns they have about paying for their education. Do it in existing conversations with admissions, financial aid, and advising teams rather than making students feel like they’re being asked to justify whether they can afford to enroll.
Just as importantly, pay attention to the questions coming up repeatedly. Those patterns can help institutions identify where students are struggling and inform the scenario planning already underway.
We may not know exactly how this will play out. But we can start listening now.